 - EN
 - EN
AI R&D CTO Compiles R&D Evidence for Employee Verification:
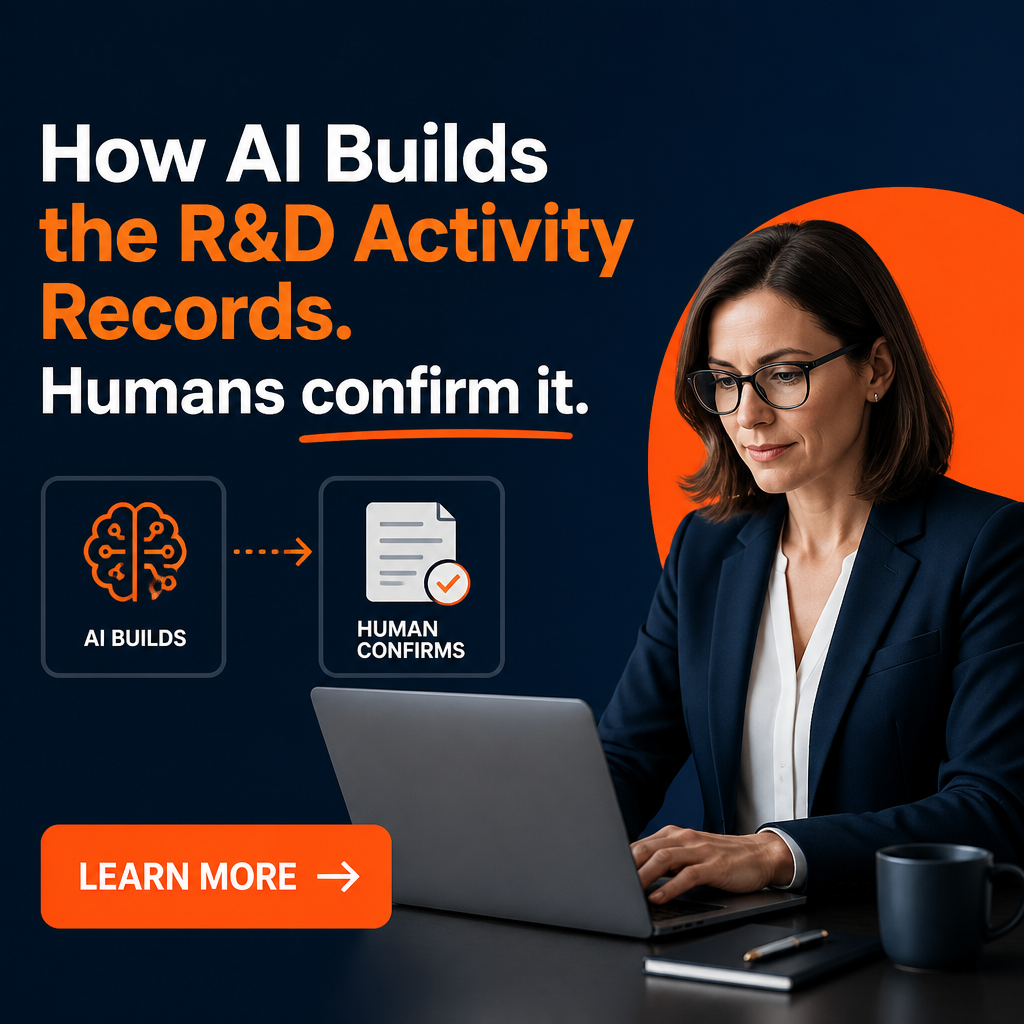
Employees shouldn’t have to become tax-credit documentation specialists. They should explain the R&D they performed. An AI R&D CTO can organize that information into a structured R&D activity record, and humans can confirm that it accurately reflects the work.
That simple shift is transforming how companies support Research and Development Tax Credits. Instead of chasing timesheets, reconstructing project histories, and scrambling for year-end documentation, teams can maintain a defensible, human-validated record of Qualified Research Activities (QRAs) and the related Qualified Research Expenses (QREs). The result: stronger compliance, faster R&D Study development, and better Business Cash Flow through smarter Tax Savings—without turning engineers into administrators.
This is also where the specialized category of AI R&D CTO becomes practical: it combines R&D Tax Credit Services discipline with AI Product Intelligence and AI Innovation Management so small and mid-sized companies can claim what they earned while improving Innovation Management and technical decision-making.
R&D Activity Record: Tracking QRAs and QREs:
An R&D activity record is more than a narrative and more than a timesheet. It’s a continuously maintained, reviewable record of what happened in R&D, who did it, when it occurred, what technical uncertainty was addressed, what experimentation occurred, and what evidence supports it.
For an R&D Tax Credit claim, this matters because a credible link is created between:
• Business components (products, processes, software, techniques, or formulations)
• Qualified Research Activities (what the team did to resolve technical uncertainty)
• Qualified Research Expenses (wages, supplies, and certain contractors tied to that work)
Traditional approaches often gather this information late, manually, and inconsistently. R&D Tax Credit Consultants then have to reconstruct the year through interviews and partial evidence. In contrast, an AI R&D CTO approach treats documentation as a living system: a structured activity record that supports Form 6765 preparation, contemporaneous documentation expectations, and audit-ready logic.
A key principle: evidence supports the activity record. It should not mechanically dictate the employee’s R&D time. For example, a burst of commits or tickets may corroborate activity—but it shouldn’t automatically convert to a percentage. Human confirmation remains the source of truth.
Use the three-step model: employee knowledge → AI structure → human confirmation:
The most defensible documentation model is human-in-the-loop, built around what your technical team actually knows.
1) Employee provides the knowledge
The engineer, developer, scientist, or technician explains:
• what they worked on
• what technical uncertainty existed
• what they tested
• what failed or changed
• which projects they worked on
• approximately how their time was divided
2) AI builds the record
The AI R&D CTO organizes this testimony into a structured format:
• projects and business components
• technical activities mapped to QRAs
• weekly activity records
• quarterly summaries
• employee time allocations
• supporting-document references (tickets, commits, test results, lab notes)
3) Human confirms
The employee or technical lead reviews:
• Is this what I actually worked on?
• Are these activities accurate?
• Does the time allocation make sense?
• Are the projects assigned correctly?
Then: confirm → correct → approve.
This model directly solves the timesheet problem. Instead of forcing continuous entry of R&D hours, employees periodically explain what they actually did. The AI reconstructs the structured activity record, and humans confirm it.
The employee supplies the technical truth. AI supplies the structure.
“The organizational, operational, and cultural significance of enlisting AI for performance measurement is difficult to overstate.”
– MIT Slan Management Review
Identify Qualified Research Activities with precision using an AI R&D CTO framework:
Many startups, software companies, manufacturers, engineering firms, and technology businesses perform qualifying work without realizing it. The challenge isn’t “doing R&D”—it’s identifying which efforts meet the criteria and documenting them correctly.
An AI Chief Technology Officer or AI Technology Advisor operating in an AI R&D CTO capacity helps teams consistently capture QRAs by prompting for the details that matter:
• What capability or performance goal was being pursued?
• What technical uncertainty existed at the start (method, capability, design)?
• What alternatives were evaluated?
• What tests, prototypes, simulations, or iterations were run?
• What results changed the direction of development?
This is especially relevant in sectors where iteration is constant—software architecture changes, manufacturing process optimization, engineering design revisions, and prototype testing. A well-formed activity record can map those iterations to a clear R&D story that supports an R&D Tax Credit claim.
The benefit for smaller companies is leverage: instead of relying solely on memory at year-end, you create a repeatable system that improves accuracy and reduces time burdens while maximizing available R&D Tax Credits.
Calculate Qualified Research Expenses from validated activity records:
Once activities are structured and confirmed, turning them into Qualified Research Expenses becomes far more straightforward.
QREs commonly include:
• Wage expenses for employees performing, directly supervising, or directly supporting qualified research
• Supply costs consumed in experimentation or prototyping
• Certain contractor costs (subject to the rules)
The activity record provides the missing link between payroll and qualified work: time allocation supported by credible technical narratives and anchored evidence.
Instead of approximating R&D percentages in a vacuum, your technical leads validate how time was divided across projects, and the documentation shows why those projects are Qualified Research Activities. This reduces risk in an IRS review and improves the quality of your R&D Study.
For many companies, the downstream impact is meaningful: better substantiation often leads to more confident claims, fewer conservative under-claims, and a clearer path to an R&D Tax Credit Refund or improved carryforward strategy—ultimately strengthening Business Cash Flow.
Replace manual R&D Studies with AI-supported documentation—while keeping humans in control:
Traditional R&D Tax Credit Services often rely on manual note-taking, spreadsheet time surveys, and narrative drafting that can take weeks. An AI R&D CTO can accelerate this by organizing information into consistent components that R&D Tax Credit Consultants and internal stakeholders can review.
What changes is not who owns the claim—it’s how the documentation is produced.
• Technical interviews become structured prompts that capture uncertainty, experimentation, and outcomes
• Time surveys become periodic human confirmations of AI-generated activity summaries
• R&D Studies become easier to assemble because the building blocks (projects, QRAs, QRE logic, evidence references) are already organized
This is not AI deciding what qualifies. It is AI compiling employee testimony and available evidence into a structured R&D activity record that the employee validates.
When done well, this reduces friction between finance and engineering: finance gets consistent records for tax substantiation, and technical teams spend less time translating their work into tax language.
Add product intelligence and technical leadership without building a full executive staff:
Beyond R&D Tax Credits, the AI R&D CTO category is designed to democratize capabilities typically reserved for large enterprises. A Virtual CTO model can provide AI Product Strategy, AI Product Intelligence, and AI Technical Advisor support that helps teams make better decisions while staying focused on execution.
For small and mid-sized organizations, this can include:
• Product strategy insights tied to technical feasibility
• Competitive benchmarking and innovation intelligence
• Emerging technology awareness that reduces rework and dead-ends
• Technical barrier resolution support through better framing of experiments and alternatives
Importantly, this guidance complements—not replaces—your internal leadership. It gives teams a way to “get out of the day-to-day bubble,” improve documentation discipline for R&D Tax Credits, and strengthen technical planning without the cost of building large internal teams.
The result is a more level playing field: additional innovation funding through Research and Development Tax Credits, improved cash flow, and stronger technical decision-making that supports AI Product Development outcomes.
Turn your R&D Tax Credit into a self-funding innovation engine:
When your R&D activity record is continuously maintained and human-validated, your R&D Tax Credit claim becomes less disruptive and more repeatable. Over time, that creates compounding benefits:
• More complete identification of Qualified Research Activities
• More accurate calculation of Qualified Research Expenses
• Faster preparation of an R&D Study
• Stronger compliance support with contemporaneous documentation
• Greater confidence in filing for R&D Tax Credits and potential refund opportunities
This is how the AI R&D CTO democratizes innovation: helping startups, micro businesses, and small companies recover R&D Tax Credits while gaining access to technical leadership and innovation intelligence previously available only to large enterprises.
To learn more about how an AI R&D CTO can enhance knowledge to world-class standards while seamlessly gaining R&D tax credits, and to get an estimate of how much your R&D Tax Credit could be, select the button below.